Finance leaders’ outlook: Navigating capital markets as a digital assets business
Key takeaways
- Capital-markets readiness starts long before a transaction. Reliable reporting, audit relationships, controls, systems and specialist finance talent need to be built before an IPO or fundraising window opens.
- Trusted data is the foundation of the modern finance function. AI, forecasting and automation only become useful once transaction data is accurate, reconciled and capable of flowing reliably through downstream systems.
- Digital-asset accounting can directly affect capital strategy. Gross-versus-net presentation, token revenue recognition and regulatory-capital treatment can change reported economics, public-company requirements and funding costs.
- The routes to capital are expanding. Digital-asset companies are using everything from SPACs and investment-grade ABS to tokenized equity as traditional investors and regulators become more familiar with the underlying businesses.
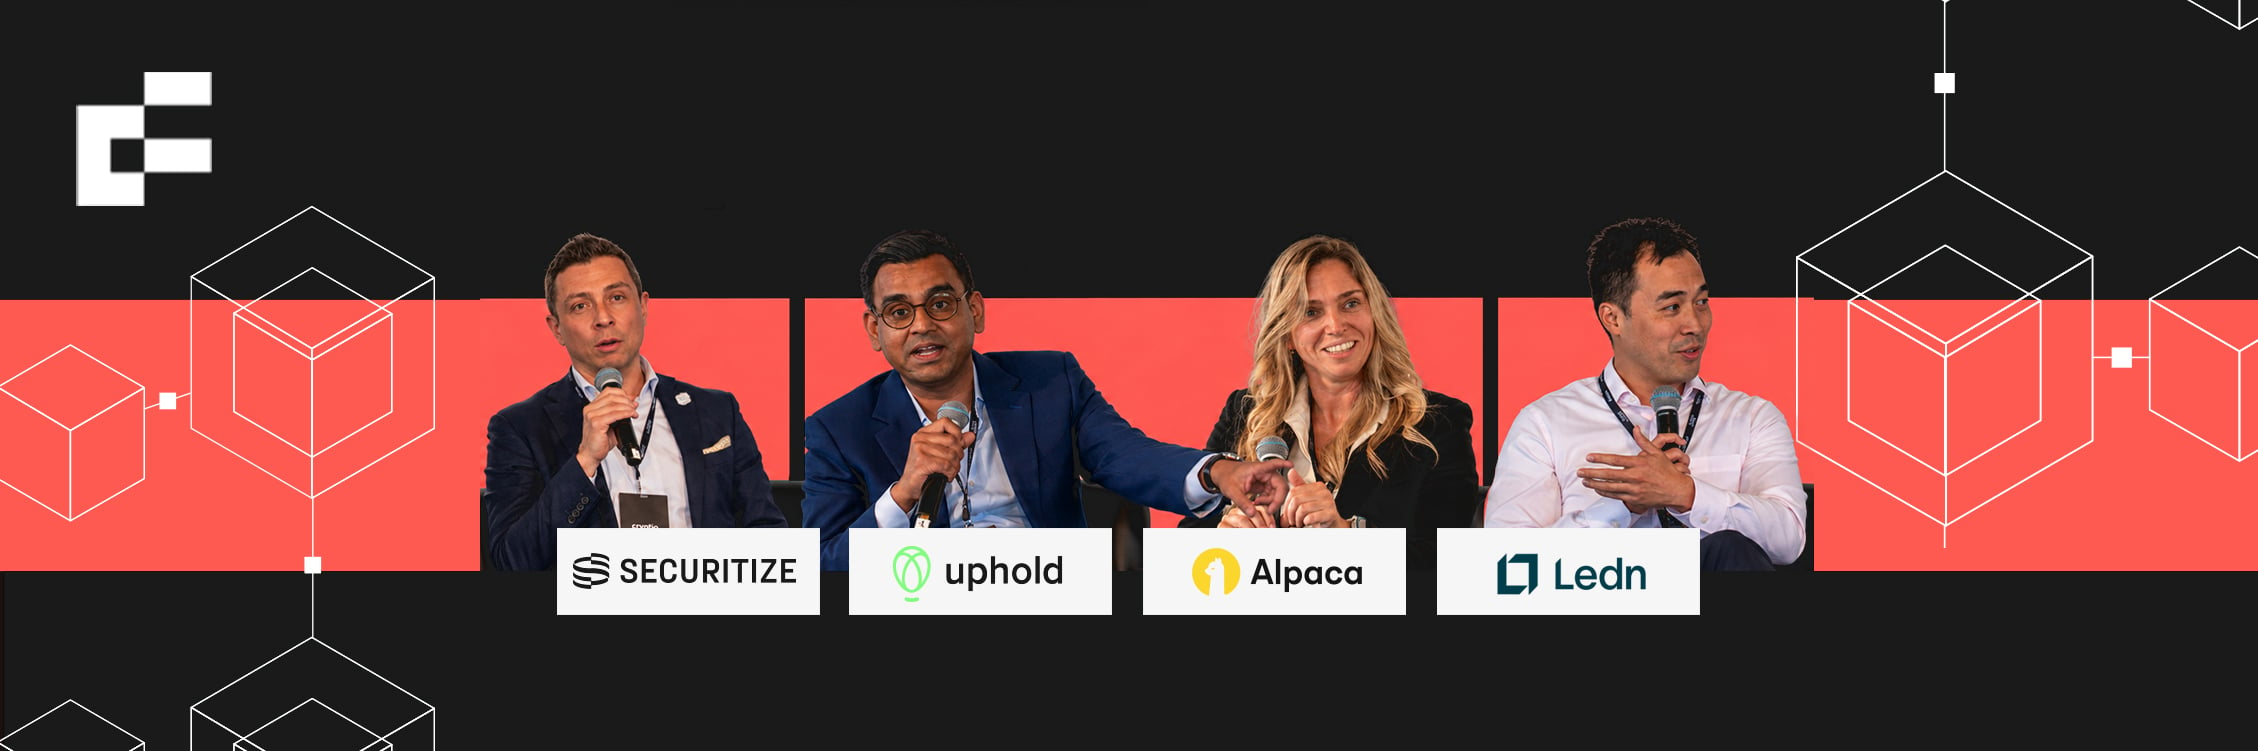
Panelists
- Thomas Wu – Chief Financial Officer | Ledn
- Nadia Asoyan – Chief Financial Officer | Alpaca
- Pankaj Soni – Chief Administrative Officer & Deputy CFO | Uphold
- Francisco Flores – Chief Financial Officer | Securitize
- Moderator: Reza van Roosmalen – Principal, Accounting Advisory Services | Deloitte
Public-company readiness starts before the IPO window opens
For a digital-asset company considering an IPO or other public-market transaction, the work starts long before bankers are formally engaged or a listing process begins.
Drawing on her experience building finance functions through Square and Robinhood, Nadia Asoyan described an approach of building systems and processes early enough that the company would eventually be capable of operating as a public business.
When she joined Robinhood at around 40 employees and before the business had meaningful revenue, she said the finance function was already being built with that future state in mind.
That meant investing early in scalable processes, faster closes, audit relationships and systems capable of supporting increasingly complex accounting and finance requirements. It also meant thinking ahead to the point where the company might need to explain its financials, controls and accounting judgments to regulators and public-market investors.
Pankaj Soni described what happens when that preparation has to be compressed.
When Uphold began preparing for the possibility of going public, the finance team had to rapidly strengthen accounting expertise, forecasting, audit readiness and reporting infrastructure. The company ultimately completed its PCAOB audit work within five months.
Reza van Roosmalen distilled the lesson simply: companies that start preparing only when a favourable IPO window arrives are usually already too late.
The market may determine when a transaction becomes attractive. The finance function needs to be ready before that happens.
The finance team moves from generalists to specialists
Public-company readiness also changes the structure of the finance organisation itself.
Francisco Flores described Securitize's finance function growing from four people to 23 as the company prepared for and completed its public-market transaction.
The bigger change was the type of people being hired. A team that had previously operated largely as generalists developed dedicated capabilities across SEC reporting, technical accounting, internal controls, internal audit, investor relations and FP&A.
That changed the CFO role too. Francisco described moving away from directly handling tasks ranging from journal entries to forecasts and toward managing specialist functions, overseeing the broader finance organisation and spending substantially more time with investors.
After becoming public, investor engagement became a weekly part of the job.
Looking back, Francisco said one thing he would have done differently as a private-company CFO was spend more time engaging with investors, analysts and the wider market earlier.
The lesson from Securitize's experience is that scaling finance is not simply a matter of adding headcount. As a company matures, the architecture of the team changes: responsibilities become more specialised, ownership becomes clearer and the CFO moves further from execution into capital allocation, communication and oversight.
AI only works if the underlying data is right
As finance teams adopt more automation and AI, Thomas Wu argued that the most important input remains unchanged.
“The underlying thing is just numbers. You can have all the right AI tools, you can have everything you want to produce that outcome, but at the end of the day, it’s what you start with.”
– Thomas Wu, Ledn
For Ledn, that means making sure the raw information behind loans, interest and other activity is accurate before it flows into reporting, forecasting or management information.
Once that foundation is reliable, finance teams can layer better reporting, forecasting and automation on top.
Thomas's conclusion was direct: “the core is always the data.”
Uphold illustrated how difficult that becomes in a digital-asset environment.
Its activity spans hundreds of cryptoassets, multiple blockchains, liquidity providers, exchanges and custody locations. Assets can sit in cold storage, on an exchange or be moving across blockchain infrastructure.
For PK, the core control question is therefore simple: if the company says it owes customers a given amount of Bitcoin, can the finance team demonstrate where that Bitcoin is?
That makes reconciliation one of the most important pieces of the operating model.
Uphold has invested across reconciliation, ERP, planning and AI tooling, but PK's description of the architecture kept returning to the same combination: data, processes, people and systems capable of validating one another.
Technology can make the finance team much more productive. It cannot compensate for an unreliable source of truth.
You cannot compress audit readiness indefinitely
Audit readiness was another recurring theme across the panel.
Nadia said companies should think about SOX and internal-control readiness well ahead of a potential listing. For many businesses, that process can begin 18–24 months before an IPO, although regulated digital-asset companies may already have some of the necessary control environment in place.
Her own approach is to keep building toward IPO-grade infrastructure even when there is no active listing plan.
Francisco made a similar point from the audit side.
Historically, digital-asset companies often struggled to find audit firms willing to take on the sector. As the market has matured, that has improved, but specialist knowledge remains critical.
For a business considering public markets, Francisco said he would start the transition toward PCAOB-standard auditing earlier if he could repeat the process.
PK's experience shows why.
Uphold's board gave the team a highly compressed timetable to complete the work required for public-company readiness. Doing so required the right audit partner, specialist external expertise and significant effort from the internal accounting team.
His retrospective assessment was memorable:
“If you paid me $5 million to do what I did five months back, I would not do it again.”
– Pankaj Soni, Uphold
The point was not that the work lacked value. PK said the investment left Uphold much better prepared. It was that years of finance-function maturity are expensive to compress into a few months.
Accounting decisions can reshape the road to market
Some of the hardest problems discussed were not about raising capital at all. They were accounting questions that could ultimately affect how a company accesses it.
PK highlighted the treatment of revenue on a gross-versus-net basis.
Because Uphold acts as principal counterparty on transactions, the accounting presentation can result in reported gross revenue running into the billions of dollars, even though PK argued that the number does not represent the economics of the business in the way an ordinary reader might interpret it.
That creates consequences beyond the income statement.
Public companies use revenue in KPIs and forecasts. Revenue thresholds can also influence whether a company qualifies for particular emerging-growth-company provisions and therefore how burdensome the route into the public markets becomes.
Reza pointed out that an accounting judgment can therefore affect the amount of readiness work required before a listing.
Nadia said she had worked through the same gross-versus-net issue previously at Robinhood and was encountering related questions again at Alpaca.
Francisco raised a different challenge at Securitize: applying ASC 606 to contracts involving tokens that may be locked or unvested, where determining the timing and treatment of revenue recognition becomes considerably more complex.
Thomas then broadened the discussion beyond accounting into regulatory capital.
For a Bitcoin-backed lender such as Ledn, the capital treatment applied to digital assets can influence which banks are willing to provide funding and at what cost. Institutions can build around those constraints using different structures, but those structures themselves introduce cost.
Across each example, the rules used to report and regulate the business affect much more than compliance.
They influence how the business looks to investors, how its balance sheet is managed and which sources of capital are economically available.
Digital-asset credit is finding its way into traditional capital markets
The second half of the panel shifted from building the finance function to what that maturity can unlock. One of the clearest examples came from Ledn.
Earlier in 2026, the company issued a $188 million asset-backed securitization backed by Bitcoin-backed loans.
The senior tranche accounted for approximately $160 million and received a BBB- investment-grade rating from S&P. According to Thomas, the transaction was roughly 2x oversubscribed despite taking place during a difficult period for Bitcoin markets.
For Ledn, the attraction of the ABS market was access to a different pool of capital.
The company had historically borrowed through bilateral facilities with individual institutions. Securitization offered a way to reach a broader set of investors already familiar with analysing structured-credit products.
But Bitcoin-backed lending does not have the decades of historical performance data available for assets such as auto loans or credit-card receivables.
That meant investors and S&P needed to understand the structure itself: how the loans were collateralised, how loan-to-value ratios worked, what happened during market stress and whether the liquidation mechanics had performed as designed.
Thomas described a roughly 50% LTV structure, giving investors significant collateral coverage.
The transaction therefore did something broader than provide funding to Ledn. It translated a crypto-native credit product into a capital-markets structure that traditional investors already understand.
That is one route through which digital-asset businesses can gain access to larger pools of institutional capital without waiting for entirely new financing markets to develop.
There is no single route to capital
The wider discussion showed how broad the capital menu has become.
Uphold has considered public markets alongside private capital and other financing options. PK's view was that companies should not raise capital simply because capital is available: there needs to be a productive use for it.
Securitize considered a traditional IPO, direct listing, SPAC transaction and remaining private before choosing the SPAC route.
Francisco said the ability to engage investors early, the structure of the chosen vehicle and the economics of the transaction all contributed to that decision. The transaction was accompanied by a PIPE of more than $200 million.
The due-diligence process remained intensive. Securitize assessed several potential vehicles before selecting one, after which the chosen counterparty conducted a detailed review across the business.
The broader point from the panel was that digital-asset businesses increasingly have access to many of the same capital-markets tools as companies elsewhere in financial services – while also beginning to experiment with routes that are specific to digital infrastructure.
Tokenized equity joins the capital menu
Securitize provides the clearest example of where those two worlds can meet.
After completing its public-market transaction, the company tokenized its own shares on Avalanche and Solana.
Francisco said the objective was to demonstrate that Securitize's model could work in practice: the company had the technology, the necessary structure and investor demand for the tokenized shares.
“We wanted to show the market that it was possible, that we had the technology, that we had the model, and there was demand for the tokens.”
– Francisco Flores, Securitize
The responses from the other CFOs were revealing.
PK said Uphold had already spoken with Securitize about the possibility of tokenizing its own securities while considering its capital-markets options.
Nadia described tokenized equity as an interesting additional option for Alpaca.
Ledn had also considered it, but Thomas said the liquidity available for the particular instrument they were assessing was not sufficient to justify moving forward at the time.
That gives a much more useful picture than assuming every security will immediately move on-chain.
For some companies, tokenized equity is already viable. For others, it is a new financing or ownership option worth keeping available. And in some cases, the economics still do not justify it.
The important change is that CFOs can increasingly include it in the conversation alongside more established choices such as private equity, debt, SPACs and traditional listings.
SEC engagement looks different than it did a few years ago
The final part of the discussion reflected on another sign of the sector's maturation: interaction with the SEC.
Francisco described Securitize's recent experience as broadly constructive, with response times considerably faster than some of the lengthy processes digital-asset companies had experienced previously.
PK suggested part of the change comes from familiarity.
A few years ago, companies could spend significant time simply explaining how crypto transactions and digital-asset business models worked. Regulators, advisers and auditors now have considerably more experience with the mechanics of the industry.
That does not eliminate difficult accounting or regulatory questions. If anything, the products being brought to market are becoming more sophisticated.
But the baseline has shifted.
Finance teams are more mature. Auditors have more digital-asset expertise. Traditional investors are developing ways to analyse crypto-native credit. Regulators have a deeper understanding of the businesses they oversee.
And companies now have more routes into institutional and public capital than they did only a few years ago.
For CFOs, the message from the panel was clear: the opportunity to access those markets depends heavily on the infrastructure built before the transaction ever begins.
About Cryptio
Cryptio is an institutional-grade data engine for accounting, reconciliation, fund administration and credit in the digital assets and AI era.
As digital-asset businesses mature, raise institutional capital and prepare for public-company scrutiny, finance teams need financial data they can trust across increasingly complex operating environments.
Cryptio connects on-chain and off-chain activity across blockchains, custodians, exchanges, lending platforms and internal systems, transforming that activity into normalized, reconciled and auditable financial records.
That gives accounting and finance teams a reliable data layer for close, reporting, reconciliation and audit – while reducing the manual work required to establish where assets sit, how transactions should flow into the books and whether operational records agree with the underlying activity.
For businesses preparing for institutional fundraising, PCAOB-standard audits, public markets or the next stage of financial maturity, Cryptio helps build the financial accounting & reporting needed before the capital-markets window opens.
Table of contents
- Public-company readiness starts before the IPO window opens
- The finance team moves from generalists to specialists
- AI only works if the underlying data is right
- You cannot compress audit readiness indefinitely
- Accounting decisions can reshape the road to market
- Digital-asset credit is finding its way into traditional capital markets
- There is no single route to capital
- Tokenized equity joins the capital menu
- SEC engagement looks different than it did a few years ago
- About Cryptio
Explore how
Cryptio can help.
Cryptio can help.